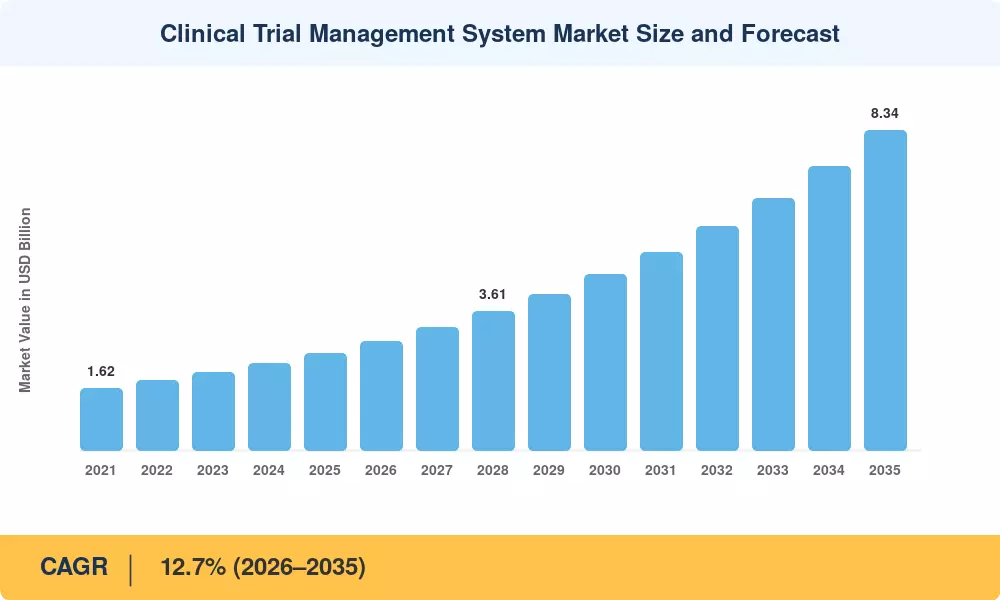
Clinical Trial Management System Market to Surge from USD 2.52 Billion in 2025 to USD 8.34 Billion by 2035-Driven by Rising Trial Complexity, Regulatory Mandate
NY, CA, UNITED STATES, September 21, 2026 /EINPresswire.com/ — As per Market Research Future, the global Clinical Trial Management System Market size is projected to reach USD 8.34 Billion by 2035 from USD 2.52 Billion in 2025, at a CAGR of 12.7% during the forecast period 2026–2035. The market opened the forecast window at USD 2.84 Billion in 2026.
The 12.7% CAGR—anchored by structural shifts in clinical research operations—is propelled by three converging forces: the rising global volume and complexity of clinical trials, with Tufts CSDD finding the average Phase III protocol now carries 263 procedures and 3.6 million data points, driving sponsors to adopt CTMS platforms for portfolio-level oversight that manual processes cannot absorb; advancements in delivery architecture, particularly cloud-based SaaS platforms that unify site payments, monitoring visits, enrollment forecasting, and regulatory document management in one environment, which significantly reduce validation burden and deployment timelines; and the integration of decentralized and hybrid trial designs, including wearable-derived endpoints, home nursing visits, and remote consent, that demand continuous, platform-based trial oversight rather than periodic review.
Global life sciences technology companies and regulatory bodies are amplifying this momentum. Global biopharma R&D spending crossed USD 300 billion in 2024, with sponsors pushing an unprecedented share of it through digital trial infrastructure. The European Medicines Agency processed over 5,000 trial transitions in the final eighteen months of the EU Clinical Trials Regulation 536/2014 migration window, making auditable, single-source trial records a compliance requirement rather than a preference, while the U.S. FDA’s September 2024 final guidance on decentralized clinical trials formalized sponsor oversight obligations for remote study activities. These forces are creating the regulatory infrastructure and sponsor demand on which the Clinical Trial Management System Market depends.
Request A Free Sample:
https://www.marketresearchfuture.com/sample_request/2054
Key Market Trends & Growth Drivers
Rising Demand for Portfolio-Level Trial Oversight
The market is witnessing an increasing demand for enterprise-grade trial management capabilities. As protocols grow structurally heavier—with the mean number of endpoints per Phase III protocol rising 27% between 2013 and 2023—more sponsors are seeking unified platforms for multi-study governance. This trend indicates a shift in buyer expectations from record-keeping toward continuous operational oversight, with CTMS platforms being recognized for their role in cycle-time reduction and deviation management. Oracle continues advancing product development through next-generation Clinical One trial management capabilities while migrating its deep legacy installed base to the cloud.
Advancements in Cloud and SaaS Delivery Models
Innovations in deployment architecture are becoming a hallmark of the industry. Technology vendors are refining validated multi-tenant cloud offerings that compress implementation timelines from eighteen months to a fraction of the cost of on-premise deployments. These advancements aim to enhance accessibility for mid-cap biotech accounts that were previously unreachable, potentially leading to broader market penetration. Cloud-based SaaS CTMS accounted for USD 1.16 billion of 2025 revenue, now the default choice for new deployments.
Integration of AI and Predictive Analytics
The incorporation of artificial intelligence into clinical trial operations is gaining traction. Tools such as predictive enrollment modeling trained on historical site performance and AI-assisted site selection are being utilized to forecast recruitment milestones and support risk-based monitoring. Veeva Systems continues investing in suite consolidation and AI-led enterprise displacement, while Dassault Systemes extended Medidata AI capabilities into site selection and enrollment forecasting, positioning operational data as a monetizable asset.
Regulatory Mandates and Decentralized Trial Designs
The rising regulatory burden on trial conduct is a primary driver. The EU’s Clinical Trials Regulation 536/2014 forced every sponsor running studies in the bloc onto the Clinical Trials Information System by 31 January 2025, retiring national portals, while the FDA’s decentralized trial guidance and January 2025 draft guidance on AI in regulatory decision-making reshaped oversight expectations. The market is projected to expand as sponsors and CROs increasingly deploy CTMS platforms to manage compliance across jurisdictions. The FDA received a record volume of commercial IND submissions in 2024, underscoring the sustained pipeline pressure on trial infrastructure.
Ask for Customization:
https://www.marketresearchfuture.com/ask_for_customize/2054
Market Segment Insights
BY SYSTEM TYPE
Enterprise-Based CTMS: Largest segment with 68.4% share in 2025, driven by sponsor and large-CRO preference for multi-study portfolio governance and reporting. Oracle maintains a deep installed base in large pharma through sustained platform innovation.
Site-Based CTMS: Fastest-growing segment at 14.1% CAGR, advancing as research sites professionalize their own operations and independent site networks consolidate. Advarra continues expanding site-facing deployments through its OnCore operations suite.
BY DELIVERY MODE
Cloud-Based SaaS CTMS: Largest and default deployment model, generating USD 1.16 billion in 2025, driven by lower validation burden and faster deployment cycles. Veeva Systems continues strengthening cloud adoption through its single-vault architecture.
Web-Based Hosted CTMS: Significant share at 32.5% in 2025, offering single-tenant control with remote access.
On-Premise CTMS: Contracting in share terms at 21.3%, concentrated in large pharma with legacy validation estates and national data localization mandates.
BY COMPONENT
Software: Largest segment with 61.5% share in 2025, anchored by core licensing and module expansion across trial portfolios.
Services: Contributed USD 0.97 billion in 2025, driven by validation, migration, configuration, and managed-hosting work that produces recurring engagement beyond the licence.
Hardware: Smaller but necessary component, supporting site infrastructure and validated computing environments.
BY END USER
Pharmaceutical & Biotechnology Companies: Largest segment with 47.8% share in 2025, due to portfolio oversight needs and regulatory accountability for study conduct.
Contract Research Organizations: Fastest-growing end user at 15.7% CAGR, as rising outsourcing penetration drives demand for configurable multi-tenancy across sponsor clients. IQVIA continues strengthening its technology-plus-CRO bundled offering.
Medical Device Manufacturers: Valued at USD 0.30 billion in 2025, lifted by EU MDR post-market clinical follow-up obligations pushing device makers into sustained evidence generation.
Academic & Research Institutes: 11.8% share, driven by grant-funded study administration and compliance requirements.
Read Detailed Insights:
https://www.marketresearchfuture.com/reports/clinical-trial-management-system-market-2054
Regional Outlook
North America — Market Leader in Trial Volume
North America leads with 43.5% of global revenue in 2025, underpinned by FDA submission volume and CRO density. The United States holds 82.1% of regional revenue, and the FDA received a record volume of commercial IND submissions in 2024. The region is a replacement market rather than a greenfield one, defined by consolidation as CRO mergers cascade platform choices across acquired books of business. The competitive landscape is characterized by continuous innovation and suite consolidation among leading life sciences technology companies.
Europe — Second Largest Market
Europe was valued at USD 0.68 Billion in 2025, lifted by the mandatory CTIS adoption deadline under the Clinical Trials Regulation 536/2014. The region benefits from coordinated multi-country assessment, which rewards platforms that can manage one dossier against many national requirements. Germany leads with 22.4% of regional revenue as the largest EU trial host by site count, while the UK’s MHRA international recognition procedure eased dual-track burden for cross-Channel programmes. Leading countries include Germany, the UK, and France.
Asia-Pacific — Rapidly Growing Market Segment
The Asia-Pacific region is the fastest-growing market, compounding at a 16.4% CAGR through 2035 as China, India, and South Korea absorb a rising share of global patient recruitment. China holds 29.6% of regional revenue on the strength of NMPA reforms and a growing domestic biotech pipeline, while India advances at an 18.4% CAGR driven by CDSCO timeline reductions and large patient pools. Japan contributes USD 0.10 billion, supported by the PMDA’s global simultaneous development push. Data residency requirements remain the principal deployment obstacle in the region.
South America and Middle East & Africa — Untapped Potential
South America holds around 5.1% of the global share, led by Brazil’s Law 14.874/2024, which replaced an unpredictable approval process with statutory review timelines—a change sponsors had lobbied for over a decade. The Middle East & Africa region, valued at USD 0.11 billion, is driven by sovereign health investment, including Saudi Arabia’s Vision 2030 Health Sector Transformation Program and South Africa’s deep investigator experience in infectious disease and vaccine trials.
Competitive Landscape and Recent Developments
The Clinical Trial Management System Market is characterized by moderate concentration and rapid platform consolidation, driven by rising trial complexity and regulatory mandates worldwide. The top five vendors hold an estimated 48–54% of global revenue, with a barbell-shaped structure: suite vendors compete for enterprise sponsor accounts while a long tail of specialists serves sites, academic centres, and device sponsors.
KEY COMPANIES AND RECENT MILESTONES
Oracle Corporation (US): Market leader with an estimated 11–14% revenue share. Offers Oracle Clinical One trial management alongside a deep Siebel CTMS estate in large pharma, actively migrating legacy customers to the cloud.
Dassault Systemes / Medidata (FR) (June 2024): Extended Medidata AI capabilities into site selection and enrollment forecasting, positioning operational data as a monetizable asset. Holds an estimated 10–13% revenue share with the strongest EDC-adjacent pull-through.
Veeva Systems (US) (September 2024): Announced expanded Vault CTMS adoption among top-20 pharma sponsors, reinforcing suite consolidation dynamics. Holds an estimated 9–12% revenue share with a single-vault architecture and the fastest enterprise displacement record.
Advarra (US) (November 2023): Broadened its site-facing operations portfolio following integration of acquired site technology assets, strengthening its leadership in the academic and site network segment with an estimated 5–7% revenue share.
Other Key Players: IQVIA (US), Parexel International (US), Clario (US), Calyx (US), Anju Software (US), Signant Health (US), RealTime Software Solutions (US), Ennov (FR).
Regulatory Milestones: EMA CTIS transition deadline passed (January 2025); FDA issued draft guidance on AI in regulatory decision-making (January 2025); FDA published final decentralized clinical trials guidance (September 2024); MHRA launched the international recognition procedure (January 2024); Brazil enacted Law 14.874/2024 (May 2024).
Future Outlook: 2026–2035
The Clinical Trial Management System Market is projected to reach USD 8.34 billion by 2035, growing at a CAGR of 12.7%, driven by rising protocol complexity, regulatory mandates, and cloud-based trial infrastructure.
New opportunities lie in:
– Expansion into emerging markets with greenfield trial infrastructure and lower-cost regional editions
– Development of AI-driven enrollment forecasting and autonomous trial operations
– Investment in site-side platform adoption and real-world evidence convergence
By 2035, the Clinical Trial Management System Market is expected to achieve substantial growth and innovation, with continuous trial oversight defining the next decade of competition.
Related Report:
https://www.marketresearchfuture.com/ja/reports/epharmacy-market-6615
https://www.marketresearchfuture.com/de/reports/epharmacy-market-6615
https://www.marketresearchfuture.com/es/reports/epharmacy-market-6615
https://www.marketresearchfuture.com/zh-cn/reports/epharmacy-market-6615
https://www.marketresearchfuture.com/ko/reports/epharmacy-market-6615
https://www.marketresearchfuture.com/fr/reports/facial-injectable-market-1527
https://www.marketresearchfuture.com/ja/reports/facial-injectable-market-1527
https://www.marketresearchfuture.com/de/reports/facial-injectable-market-1527
https://www.marketresearchfuture.com/fr/reports/genetic-testing-market-2009
https://www.marketresearchfuture.com/ja/reports/genetic-testing-market-2009
https://www.marketresearchfuture.com/de/reports/genetic-testing-market-2009
https://www.marketresearchfuture.com/fr/reports/intravenous-solution-market-1235
https://www.marketresearchfuture.com/ja/reports/intravenous-solution-market-1235
https://www.marketresearchfuture.com/de/reports/intravenous-solution-market-1235
https://www.marketresearchfuture.com/fr/reports/life-sciences-bpo-market-10167
Market Research Future
Market Research Future
+1 855-661-4441
email us here
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery